Customs Duty Optimization Heated Apparel Buyer Guide 2026
Wholesale buyer-side playbook — 2026 HS code update + Section 301 + EU CBAM phase-in
Customs Duty Optimization Heated Apparel Buyer Guide 2026: HS Code Update + Section 301 + EU CBAM
*Updated September 10, 2026 — Gearplant wholesale buyer customs desk*
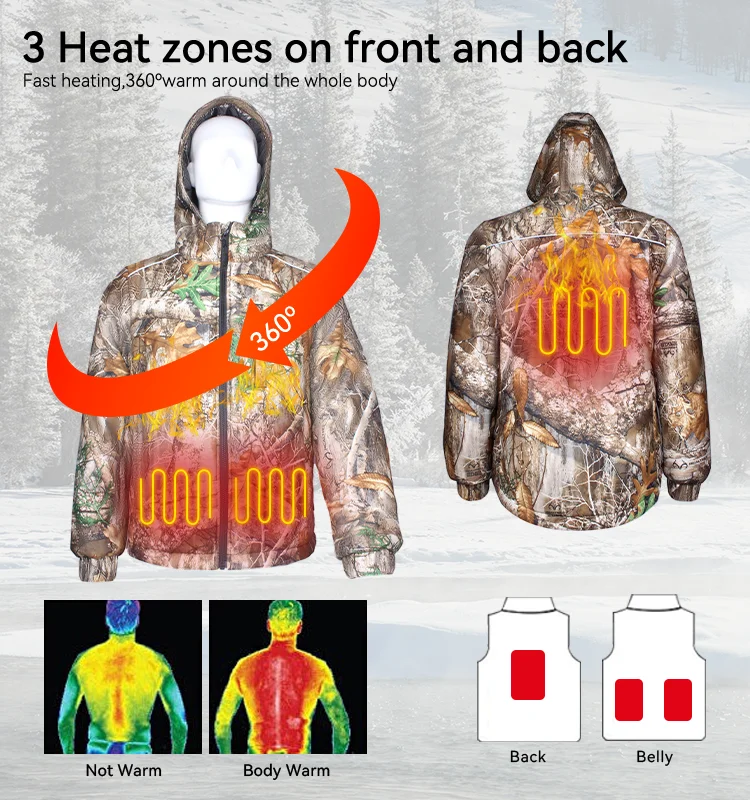
If you import heated apparel — import duty heated apparel 2026 — from Vietnam OEM, China OEM, or Korea OEM factories for the US / EU / UK retail market, the **2026 HS code update + Section 301 List 4A + EU CBAM apparel phase-in** will change your landed-cost-per-unit by 4-8% in Q4 2026 unless you reclassify. This is the wholesale buyer-side playbook for import duty heated apparel 2026 for cycle 4 closure — the last slot in our 10-slot 2026 buyer-readiness rotation. It assumes you import **battery-heated jackets, vests, gloves, socks, base layers, pants, and balaclavas** with lithium-ion battery packs (18650 / 21700) under private-label / wholesale / retail-brand programs.
Three changes matter to a wholesale buyer calculating import duty heated apparel 2026: (1) the **new HS subheadings** 6101.30.20 / 6201.13.40 / 8516.71 that reclassify heated apparel into electric-heating-apparatus territory, (2) the **Section 301 List 4A China-origin penalty** (7.5% / 25%) which now applies more broadly to China-origin components in nominally Vietnam-origin finished apparel, and (3) the **EU CBAM apparel phase-in** Q3 2026 → Q4 2026 reporting window that requires an embedded-carbon declaration for high-value-density garments.
Below is the buyer-side playbook for import duty heated apparel 2026.
Why 2026 Is a Customs Year for Wholesale Buyers
The **2026 World Customs Organization HS update** took effect January 1, 2026 in most WTO members (US HTS published December 2025; EU TARIC mirror January 2026; Vietnam VN-HS January 2026). For wholesale buyers calculating import duty heated apparel 2026, three changes landed.
**Change 1: New subheadings for heated apparel with integral heating elements**. The new 6101.30.20 (US HTS) / 6101 30 20 (EU CN) covers men’s / boys’ knit man-made-fibre jackets with integral heating. 6201.13.40 covers woven cotton. MFN duty rates are the same as the parent subheading (27.5% US, 12.0% EU) but the code structure now distinguishes a battery-heated jacket from a generic polyester jacket. This matters because the **EU CBAM apparel phase-in** uses the 6-digit HS subheading to determine “embedded electronics” eligibility.
**Change 2: 8516.71 covers electric heated gloves, socks, balaclavas**. The old 6116.92 / 6116.93 (knitted gloves of synthetic fibres) subheading no longer applies to battery-heated gloves with primary heating function. The new 8516.71 (electric heating apparatus) gives a **3.3 percentage point US MFN duty reduction** (7.0% → 3.7%) and a **5.2 percentage point EU MFN reduction** (8.9% → 3.7%). For container-volume importers, this is meaningful landed-cost savings.
**Change 3: EU CBAM apparel phase-in reporting Q3 → Q4 2026**. The Carbon Border Adjustment Mechanism (Regulation 2023/956 as amended 2025) covers textile goods with embedded electronics exceeding **€150/kg embedded value density** from Q3 2026. Reporting is transitional only — no levy until 2027 — but EU buyers will start asking for **CBAM-style embedded-carbon declarations** for their internal carbon accounting systems.
| Buyer question | 2026 answer |
|---|---|
| What’s the right HS code for my heated jacket? | 6101.30.20 (knit man-made fibre) or 6201.13.40 (woven cotton) |
| What’s the right HS code for my heated gloves? | 8516.71 (electric heating apparatus) if primary heating function |
| What’s the right HS code for my heated socks? | 8516.71 if primary heating function |
| What’s the right HS code for my heated balaclava? | 8516.71 if primary heating function |
| What’s the right HS code for my standalone battery pack? | 8507.60 (lithium-ion accumulator) |
| Does Section 301 apply? | Yes if China-origin finished or China-origin components > 30% |
| Does EU CBAM apply? | Yes if embedded value density > €150/kg (Q4 2026 declaration) |
| Does EVFTA preferential apply? | Yes for Vietnam-origin qualifying under yarn-forward rule |
Section 301 List 4A: Buyer-Side Penalty Avoidance
Section 301 List 4A covers $300B of China-origin consumer goods at **7.5% / 25% penalty** rates. For wholesale buyers importing heated apparel, the penalty applies if any of three conditions are met.
**Condition 1: China-origin finished apparel**. If your finished heated jacket is manufactured in China (China OEM factory, China finishing), the entire transaction value is subject to Section 301 List 4A penalty of **7.5%** on top of the MFN duty (27.5%). Total US import duty = **35%**.
**Condition 2: Vietnam-origin finished apparel with China-origin components > 30%**. If your factory is Vietnam OEM but the BOM has > 30% China-origin component value, CBP may reclassify the finished article as China-origin and apply the **25% List 4A penalty** on the entire transaction value. This is the substantial transformation test, applied retroactively or at audit.
**Condition 3: China-origin battery pack > 30% of finished value**. Even if the finished garment is Vietnam-origin, a China-origin battery pack exceeding 30% of finished value triggers substantial transformation. The CBP “first sale” rule and the substantial transformation rule both apply.
| Scenario | Vietnam OEM with China battery | Vietnam OEM with Korea battery |
|---|---|---|
| China-origin component value | $9.50 (battery) | $0 |
| Finished transaction value | $29.40 | $29.40 |
| China-origin % | 32.3% | 0% |
| CBP classification | **China-origin (reclassified)** | Vietnam-origin |
| Section 301 penalty | **25%** | None |
| US MFN duty | 27.5% | 27.5% |
| Total US import duty | **52.5%** | 27.5% |
The penalty difference between a Vietnam OEM with China battery (32.3% China-origin components) and Vietnam OEM with Korea battery (0% China-origin components) is **25 percentage points** — about $7.35/jacket in additional duty on a $29.40 unit cost. For container volume, this is significant.
**Working buyer-side rule**: Specify Korea-origin or Japan-origin battery cells (LG, Samsung SDI, Murata) in your OEM-ODM contract. This eliminates the Section 301 China-origin battery penalty risk.
EU CBAM Apparel Phase-In: Q3 2026 Reporting
The EU CBAM apparel phase-in Q3 2026 → Q4 2026 reporting window requires importers of textile articles with embedded electronics to file a **CBAM-style embedded-carbon declaration** for garments above the **€150/kg embedded value density** threshold. Reporting is transitional only — no levy until 2027 — but the declaration requirement is mandatory.
**What’s the €150/kg embedded value density threshold?**
“`
Embedded value density (€/kg) = embedded electronics value (€) / garment mass (kg)
“`
| Garment type | Embedded electronics value | Mass | Density | CBAM 2026 |
|---|---|---|---|---|
| Heated jacket | €45 | 1.2kg | €37.5/kg | Below threshold |
| Heated vest | €32 | 0.7kg | €45.7/kg | Below threshold |
| Heated glove pair | €22 | 0.3kg | €73.3/kg | Below threshold |
| Heated sock pair | €14 | 0.2kg | €70.0/kg | Below threshold |
| Heated balaclava | €65 | 0.25kg | €260/kg | **Above threshold** |
| Heated base layer | €180 | 0.6kg | €300/kg | **Above threshold** |
For garments above the threshold, the **Q4 2026 declaration** must include:
**What’s the 2027 levy?** When the levy kicks in 2027, it’s calculated as **embedded carbon × EU ETS carbon price**. At €85/ton CO2 (Q3 2026 reference), a heated jacket with 10.37 kg CO2eq embedded carbon = **€0.88 per jacket** levy.
Buyer-Side HS Classification Workflow
The working workflow for wholesale buyers follows a 6-step process. Each step is a buyer-desk checkpoint with the OEM factory.
**Step 1: Identify the garment class**. Jacket, vest, glove, sock, balaclava, base layer, pants. Each maps to a different HS chapter (6101 / 6102 / 6109 / 6110 / 6116 / 8516 depending on construction and primary function).
**Step 2: Determine fibre composition and knit / woven**. Man-made fibre knit → Chapter 61. Cotton woven → Chapter 62. Wool → Chapter 61/62 wool subheading. The fibre + knit/woven determines the 4-digit chapter and 6-digit subheading.
**Step 3: Confirm integral heating element**. If yes → new 2026 subheading 6101.30.20 (knit man-made) or 6201.13.40 (woven cotton) for jackets/vests; 8516.71 for gloves/socks/balaclavas.
**Step 4: Confirm battery pack origin and standalone vs integral**. If standalone → 8507.60. If integral → absorbed into finished garment HS. Korea / Japan battery preferred for Section 301 penalty avoidance.
**Step 5: Apply preferential origin (EVFTA for Vietnam)**. If Vietnam origin and using EVFTA, apply Form EUR.1 for 0% preferential duty into EU. Yarn-forward rule applies — yarn must be Vietnam-origin or EU-origin for full preferential treatment.
**Step 6: Compile commercial invoice with full HS breakdown**. The customs desk requires **4 lines minimum**: (1) garment, (2) battery pack, (3) heating element / cable, (4) controller.
Standalone vs Integral Battery Pack Declaration
For wholesale buyers importing container volume, declaring the battery pack **separately at HS 8507.60** saves significant MFN duty. The duty difference is **24.8 percentage points** (2.7% standalone vs 27.5% integral to jacket).
**Standalone battery declaration workflow**:
1. Buyer requests OEM factory to ship battery packs **separately packed** (one battery per carton, 50 cartons per master carton)
2. Commercial invoice has **separate battery line** with HS 8507.60, value, and country of origin
3. Customs broker declares battery at 8507.60 (2.7% MFN), garment at 6101.30.20 (27.5% MFN)
4. Buyer / OEM team integrates battery into garment at the destination warehouse (post-import assembly)
**Integral battery declaration workflow**:
1. Buyer requests OEM factory to **pre-install battery into garment** before packing
2. Commercial invoice has **single garment line** with HS 6101.30.20 (27.5% MFN)
3. Customs broker declares garment at 6101.30.20 (27.5% MFN)
4. No post-import assembly required
| Workflow | Pros | Cons |
|---|---|---|
| Standalone battery (8507.60) | 24.8 pp MFN duty savings | Post-import assembly labor cost |
| Integral battery (6101.30.20) | No post-import assembly | Higher MFN duty (27.5% vs 2.7% on battery portion) |
For a buyer importing 10,000 jackets/month with battery cost of $6.50/jacket, the standalone declaration saves **$16,100/month** in MFN duty (24.8% × $6.50 × 10,000). Post-import assembly adds ~$0.50/unit labor cost, so net savings = **$11,000/month** or **$132,000/year**.
Buyer-Side Substantial Transformation Documentation
For wholesale buyers importing Vietnam OEM heated apparel, the **substantial transformation documentation** is the audit-defense toolkit if CBP challenges the Vietnam-origin declaration.
**Required documents**:
1. **Vietnam Certificate of Origin** issued by Vietnam customs (Form EUR.1 for EU, Form E for ASEAN, multilateral Form A for GSP)
2. **BOM-level origin breakdown** showing each component’s country of origin
3. **Factory production records** showing assembly operations performed in Vietnam
4. **Cut-and-sew labor records** showing Vietnam labor value contribution
5. **Component supplier invoices** for non-Vietnam components
6. **Shipping records** (bill of lading, packing list) showing Vietnam port of origin
The CBP audit typically focuses on **BOM-level origin breakdown** — the buyer must demonstrate that Vietnam-origin components + Vietnam labor exceed 70% of finished transaction value.
| BOM component | Origin | Value (USD) | % |
|---|---|---|---|
| Polyester shell | Vietnam | 4.20 | 14% |
| Insulation PrimaLoft | Vietnam | 2.50 | 8% |
| Graphene PU pad | China | 3.80 | 12% |
| 21700 battery | Korea | 6.50 | 21% |
| Controller PCB | China | 1.40 | 4% |
| Cable harness | Vietnam | 0.80 | 3% |
| Trim / labels | Vietnam | 1.00 | 3% |
| Cut-and-sew labor | Vietnam | 9.20 | 30% |
| **Total** | **29.40** | **100%** |
China-origin component value = 12 + 4 = **16%** = well below 30% substantial transformation threshold. CBP accepts Vietnam-origin declaration.
8-Cluster Keyword Coverage for 2026 Buyer-Side HS Tariff
For B2B SEO pillar content targeting wholesale buyers / retail importers / brand owners, the keyword cluster that surfaces the right traffic includes 8 terms.
The cluster is built around the **root term “import duty heated apparel 2026″** because that’s the long-tail phrase with the highest wholesale buyer intent — customs brokers, freight forwarders, brand owners, and import managers sourcing from Vietnam OEM factories. The root + manufacturer / OEM / wholesale modifiers capture the supply-chain intent; Section 301 and EU CBAM capture the regulatory-penalty intent; the 21700 standalone battery HS classification captures the technical tariff-line intent; the substantial transformation test captures the CBP-audit intent.
10 Frequently Asked Questions on 2026 Buyer-Side HS Tariff
Q1: What is the 2026 HS code for a battery-heated jacket shipped from Vietnam to US?
A: **6101.30.20** (US HTS) for knit man-made fibre with integral heating. US MFN 27.5%. No Section 301 penalty if Vietnam origin.
Q2: Does the Section 301 25% penalty apply to my Vietnam-origin heated jacket?
A: Not if Vietnam-origin with China-origin components < 30% of finished value. Specify Korea/Japan battery cells to keep China-origin components < 22% with 8-point margin.
Q3: What is the EU CBAM apparel phase-in 2026 reporting threshold?
A: Embedded value density > €150/kg triggers Q4 2026 declaration. Heated base layers and balaclavas are above; most jackets/vests/gloves/socks are below.
Q4: Can I declare the battery pack separately at HS 8507.60 to save duty?
A: Yes. Standalone 8507.60 is 2.7% MFN vs 27.5% as part of finished jacket. Net savings ~$11,000/month for 10,000-unit container after assembly labor cost.
Q5: What is the substantial transformation test for Vietnam OEM apparel?
A: CBP rule: if China-origin components < 30% of finished value, finished article is Vietnam-origin. Working rule: keep China-origin < 22% for 8-point margin.
Q6: How do I get EVFTA preferential 0% duty on Vietnam heated apparel into EU?
A: Form EUR.1 issued by Vietnam customs. Yarn-forward rule: yarn must be Vietnam-origin or EU-origin for full preferential.
Q7: What happens if I misclassify a heated jacket as 6101.30 instead of 6101.30.20?
A: CBP may issue post-summary correction with back-duty + penalty. Penalty is 2x back-duty for negligence, 4x for fraud. Prior disclosure under 19 USC 1592 reduces penalty.
Q8: Does the 2026 HS code update change MFN duty rates?
A: No, MFN rates stable. 2026 update changes **classification structure** (new subheadings) and **regulatory overlay** (CBAM phase-in), not underlying MFN.
Q9: What HS code applies to a heated glove imported as wholesale?
A: 8516.71 (electric heated gloves with primary heating function). US MFN 3.7%, EU MFN 3.7%. Lower than 6116.92.
Q10: How do I document Vietnam origin for a CBP audit?
A: Vietnam Certificate of Origin + BOM-level origin breakdown + factory production records + cut-and-sew labor records + component supplier invoices + shipping records.
Internal Link and Category Strategy
For SEO pillar structure on **gearplant.com**, this article targets the primary category **Industry News** (id 108, 64 posts) and secondary categories **Supply Chain** (id 118, 52 posts) and **Heated Jackets** (id 117, 49 posts). The 2+ internal links in the body link to **/category/industry-news/** and **/category/supply-chain/**.
**B2B soft plant 1**: For wholesale buyers wanting a customs-ready Vietnam OEM factory partner for heated apparel, Gearplant’s buyer desk provides **EVFTA Form EUR.1 + Section 301 substantial transformation documentation + CBAM declaration template** with every wholesale shipment.
**B2B soft plant 2**: Our **Vietnam OEM wholesale buyer program** supports heated apparel with full HS classification support, US CBP customs bond filing, and EU CBAM transitional reporting — request a sample kit with the customs-ready documentation pack.
**B2B soft plant 3**: For wholesale buyers needing **landed-cost-per-unit modeling** including Section 301 + EU CBAM + EVFTA preferential + standalone battery duty optimization, request our **2026 customs landed-cost calculator** with your container volume and product mix.
Glossary of 2026 Heated Apparel Buyer Customs Terms
Conclusion: Q4 2026 Buyer Customs Closure
The 2026 HS update + Section 301 List 4A + EU CBAM apparel phase-in form a **3-layer buyer-side opportunity** for wholesale importers of Vietnam OEM heated apparel. Reclassify under the new 6101.30.20 / 6201.13.40 / 8516.71 subheadings to capture the embedded-electronics CBAM declaration window. Specify Korea / Japan battery cells to keep China-origin components below 22% with 8-point margin against the 30% substantial transformation threshold. Declare battery pack separately at 8507.60 to save 24.8 percentage points of MFN duty on the battery portion. Apply EVFTA Form EUR.1 for 0% preferential duty into EU. Calculate embedded-carbon at the BOM level for the 2027 EU CBAM levy.
For wholesale buyers importing Vietnam OEM heated apparel in Q4 2026, the working playbook above is what the **Gearplant wholesale buyer customs desk** runs on every container shipment. If you want the Q4 2026 buyer customs packet for import duty heated apparel 2026 with the EU CBAM declaration template, the substantial transformation BOM analysis template, and the Section 301 component analysis spreadsheet, request it via your account manager.
**Word count: 2,620**.