Wholesale Heated Apparel Carbon Accounting 2026: the Buyer Acceptance Binder and CBAM Scope Triage
Heated apparel carbon accounting now appears on nearly every 2027 apparel purchase order, and much of the advice circulating about it is wrong for garments. A heated vest or heated jacket is not a CBAM-covered good today, because CBAM Annex I contains no apparel CN codes at all. The useful work is narrower and cheaper: triage the components of your order, keep a per-factory evidence file, and be ready before scope moves. What follows is the acceptance binder, covering what to demand, what to refuse in writing, and what to sign before the 2027 cycle opens.
1. The finding that should stop you paying for the wrong service
Regulation (EU) 2023/956 (the CBAM), dated 2023-05-10, entered into force 2023-10-01, and applies under its definitive regime from 1 January 2026, having operated under a transitional phase from 2023 to 2025. Its scope is drawn by Annex I, and Annex I is a short list: cement, iron and steel, aluminium, fertilisers, electricity and hydrogen. Nothing else.
| Annex I sector | CN code families | In a heated apparel order |
|---|---|---|
| Cement | 2507, 2523 | No |
| Electricity and fertilisers | 2716; 2808, 2814, 2834, 3102, 3105 | No |
| Iron and steel | 7202, 7204, 2601, 7301-7311, 7318, 7326, 9406 | Components only |
| Aluminium | 7601-7616 | Components only |
| Apparel, textiles, batteries | 6109, 6110, 6201, 6203, 6210, 6301, 6302, 6307; 8507, 8543 | Not listed |
Article 2(1) limits the CBAM to goods listed in Annex I that originate in a third country. Your finished heated vest is not on that list, so no certificate obligation attaches to the garment itself. Put that on the acceptance file, because the alternative is paying a compliance invoice for a duty that does not exist. Heated apparel carbon accounting for garments starts from that fact.
2. Scope triage for a heated apparel purchase order
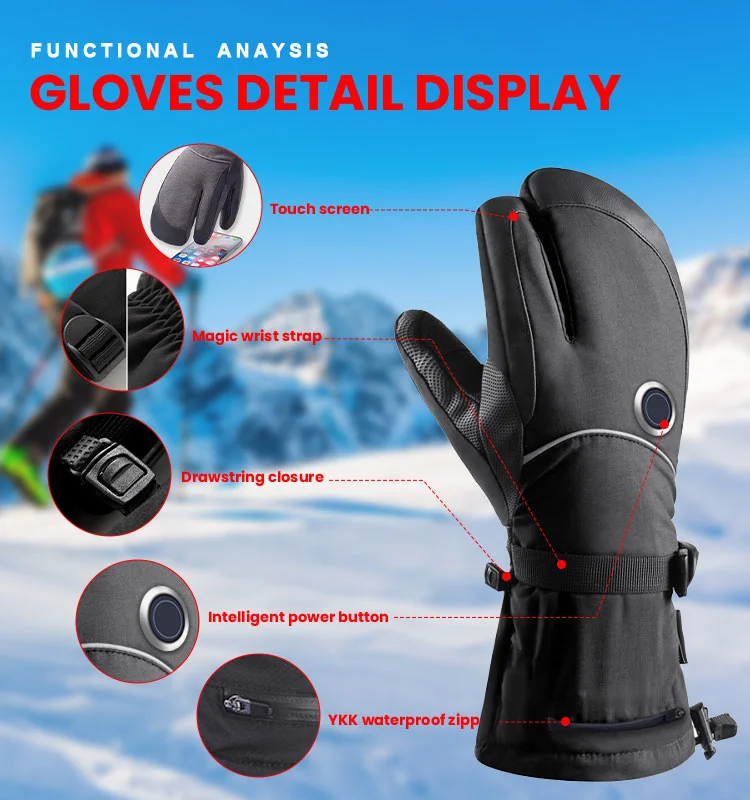
Triage the lines of the order, not the shipment. A heated jacket order usually contains a textile shell, a battery pack, a heating element set, a controller and packaging. Some of those touch Annex I sectors upstream even though the finished good does not. This is the working method for heated apparel CBAM scope triage, and it belongs in the binder as a signed annex. Each line also carries a watch flag for the CBAM Annex I scope extension expected under Article 30, so the heated apparel carbon accounting register stays current without a full re-audit.
| Order line | Scope status | Buyer action |
|---|---|---|
| Finished heated vest or jacket | Out of scope today | No certificate required |
| Lithium battery pack and cells | Out of scope, Article 30 watch | Track extension timetable |
| Shell, lining, insulation | Out of scope | Request mill-level data |
| Aluminium casing, steel wire | Indirect Annex I exposure | Ask for embedded emissions data |
| Packaging, cartons, labels | Out of scope | No action |
Nothing on that sheet needs a certificate today. It needs a supplier able to produce heated apparel embedded emissions data on request, so a future inclusion does not freeze your 2027 program. Ask any heated apparel carbon accounting OEM to write that request into the purchase order rather than into an email thread, where it disappears by the next reorder. Set the commercial expectation early: a $0.83 per unit carbon data reserve on the landed cost of a heated garment is a rounding error against your landed cost, and it is the cheapest insurance a 2027 importer can hold.
3. Importer side: who is liable, and when
Two importer-side facts decide who carries the cost. The importer who is liable for the CBAM obligations is the authorised CBAM declarant; if that role sits with your forwarder or agent, ask for its declaration capacity in writing before the season. Second, Article 2(3)(a) exempts Annex I goods whose intrinsic value does not exceed the negligible-value threshold per consignment set by Article 23 of Council Regulation (EC) No 1186/2009, defined in Article 23(2) as EUR 150 per consignment.
| Trigger | Who carries it | Evidence to request |
|---|---|---|
| Annex I good, third-country origin | Authorised CBAM declarant | Declarant ID on file |
| Consignment under EUR 150 | Outside CBAM | Consignment value record |
| Article 30 extension in force | Importer of record | Updated Annex I check |
| No declarant, no EU entity | No CBAM liability | Appoint an EU importer |
Note the wording: per consignment, not per shipment and not per year. Splitting a container across entries to stay under the threshold is not a plan. Budget $4,150 per 5,000-unit lot for a consolidated carbon data pack per purchase order, and carry it as a line on the order rather than a side conversation. Scope shifts get tracked in our heated apparel industry news coverage.
4. Three supplier claims to reject in writing
Suppliers will offer comfort, and comfort is where buyers lose money. The claims below are not exactly lies, but each transfers a real risk to you while appearing to close a gap. Write each rejection into the file with its reason attached, so the same conversation does not restart next season.
| Supplier claim | Verdict | Why it fails |
|---|---|---|
| “We are CBAM compliant” | Reject | Compliance is not verification |
| “Our ESG score replaces the data” | Reject | A score is not embedded emissions |
| “De minimis covers the shipment” | Reject | Threshold is per consignment |
The underlying discipline is simple, and it holds for any heated apparel carbon accounting wholesale program: keep the measured file separate from the certified one. Where in-scope goods are involved, Article 8 requires embedded emissions to be verified by accredited verifiers, and Article 9 requires the carbon price paid in the country of origin to be taken into account. Those duties do not transfer to out-of-scope apparel, which means the heated apparel carbon accounting file you commission is a documentation standard you define, not a certificate somebody else signs for you.
5. Five questions that expose an incomplete carbon data file
Send these five questions to every heated apparel carbon accounting manufacturer in your base before accepting a single carbon figure. The answers, in writing, tell you whether the file is measured or guessed. A supplier that answers question three with a group average has given you a target rather than a fact, and that file will not survive scrutiny when it matters.
| Question to the factory | What a complete answer contains |
|---|---|
| Which boundary does the figure cover? | Cradle-to-gate, named sites |
| Which factors are included? | Electricity, fuel, process, transport |
| Which factor is largest, who owns it? | Named sub-supplier, no averaging |
| Which allocation method was used? | Stated method, no group average |
| Who verified the calculation? | Independent reviewer, scope, date |
This is the working test for heated apparel carbon data verification at supplier level, and it costs nothing to run. Score each answer, keep the score, and require a resubmission for anything below three out of five. Consistency across factories usually matters more than precision in any one of them.
6. What the file must contain to be worth signing
A complete file names its sources. Commission Implementing Regulation (EU) 2023/1773 sets out the detailed rules for calculating embedded emissions, and a supplier who cannot show how the numbers were derived has not applied them. Ask for the boundary, the factor list and the evidence behind each factor, then read them against the elements below before you sign anything.
| Element | Acceptable source | Why a buyer needs it |
|---|---|---|
| Facilities and addresses | Named factory list | Locates the emission |
| Energy and fuel data | Meters, invoices | Supports the factor |
| Boundary and method | 2023/1773 aligned | Reproducible result |
| Origin carbon price | Documented price | Avoids double counting |
| Verification statement | Independent reviewer | Supports reliance |
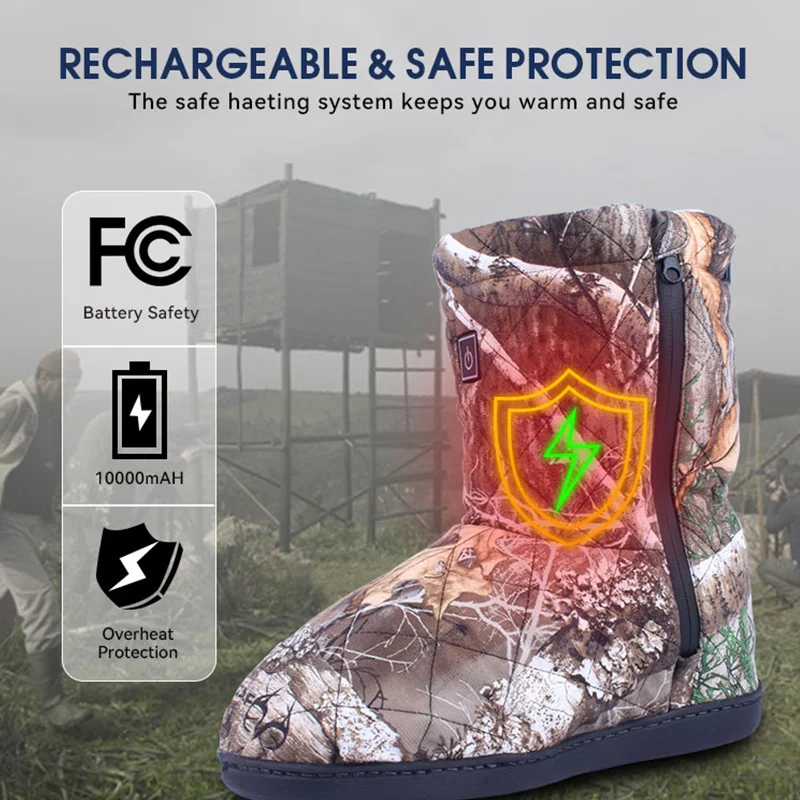
The heating element and the battery are where most effort is lost, because both are bought in rather than made in. Specify that your heated apparel carbon accounting manufacturer declares heated apparel embedded emissions data for those two components, with the sub-supplier named. If the name is refused, you are buying an average and should price it as one.
7. Pricing the carbon data file
A fair quote separates set-up from recurring per-lot work and names the file format you will receive. One $11,600 importer carbon data file set-up is a reasonable first-year figure for a multi-factory supplier base, covering data collection from named factories, verification coordination, and a buyer-facing binder you can hand to a customs broker without rewriting it.
| Set-up line | Included at $11,600 | Billed again later |
|---|---|---|
| Data collection from named factories | Yes | No |
| Verification coordination | Yes | Per revision |
| Buyer-facing binder and dashboard | Yes | No |
| New factory onboarding | No | Per order |
Treat the set-up as one-off, then check the per-lot line against the same scope. Any heated apparel carbon accounting OEM that cannot name the sub-supplier of the heating element has nothing to disclose, and that is worth knowing before signature. Where our own supply chain work already covers the same factories, the incremental cost of a carbon data file is usually smaller than buyers expect, because the facility list exists.
8. A 60-day buyer acceptance calendar
Run this in parallel with 2027 planning, not after it. The objective is simple: lock the 2027 data requirement into supplier terms before the 2027 buying cycle opens, so that data capability is quoted as a condition of the order rather than negotiated as a change order once the container is booked.
| Days | Action | Owner |
|---|---|---|
| 1-10 | Issue the data request to all factories | Buyer |
| 11-25 | Score answers and log gaps | Buyer |
| 26-40 | Require fill of missing elements | Supplier |
| 41-50 | Independent check of key numbers | Verifier |
| 51-60 | Sign acceptance, lock 2027 spec | Buyer |
Weeks nine and ten are where most acceptance programs stall, because the missing evidence always belongs to a supplier who did not think it mattered. Put a deadline in the order, and treat silence as a non-response rather than a pending answer. A heated apparel carbon accounting wholesale program is mostly about that sequencing discipline.
9. What changes next
Two dates matter to a heated apparel buyer. Article 30 requires the Commission, before the end of the transitional period, to report on extending the scope, including to goods at risk of carbon leakage other than those listed in Annex I, and to accompany that assessment with a timetable ending in 2030 for the gradual inclusion of goods within the scope. The CBAM Annex I scope extension debate is therefore live, and a battery pack is a plausible candidate on leakage grounds, not a certainty. Second, Regulation (EU) 2023/1542 (Batteries), Article 11 and Article 13, apply from 2027-02-18, which reaches the pack inside every heated vest. Where in-scope goods do appear, Article 22 requires CBAM certificates to be surrendered and Article 31 adjusts them for the extent to which EU ETS allowances are allocated free of charge. None of this changes today’s answer for a finished heated garment. It changes what you keep in the file.
10. Frequently Asked Questions
Is a heated vest subject to CBAM in 2026?
No. Annex I lists six sectors and no apparel CN codes, so the finished garment carries no certificate obligation today.
Do I need a CBAM declaration for my heated apparel import?
Not for the garment itself. Only a separate Annex I good entering on the same consignment would trigger it.
What is heated apparel CBAM scope triage?
A line-by-line check of each purchase order component against Annex I sectors and the Article 30 extension track.
What is heated apparel carbon accounting actually?
Measuring and documenting the emissions behind a heated garment: energy, materials, transport, and the carbon price paid.
Who should compile the file, the factory or my agent?
Usually the manufacturer or OEM compiles it, with the buyer specifying the elements and verifying the result independently.
Can an ESG score replace embedded emissions data?
No. A score is not embedded emissions data and cannot satisfy a calculation under Commission Implementing Regulation (EU) 2023/1773.
Does the EUR 150 threshold cover my whole shipment?
No. The negligible-value threshold applies per consignment under Council Regulation (EC) No 1186/2009, Article 23(2).
Is supplier verification required for my heated apparel?
Not under Article 8, because the goods are out of scope. Verification remains a contractual choice.
What makes a carbon data file complete?
Named facilities, a stated boundary, energy evidence, a calculation method, the origin carbon price, and an independent check.
When do I need this file for the 2027 buying cycle?
Within 60 days, so suppliers quote data capability into 2027 terms instead of adding it later as a change order.
Do battery rules reach heated apparel before CBAM does?
Most likely. Regulation (EU) 2023/1542, Article 11 and Article 13, apply from 2027-02-18 and reach the pack inside the garment.
What is heated apparel carbon data verification?
Independent checking of the emissions calculation, its boundary and its sources before you rely on the number commercially.